Cleaning Up Before Documenting
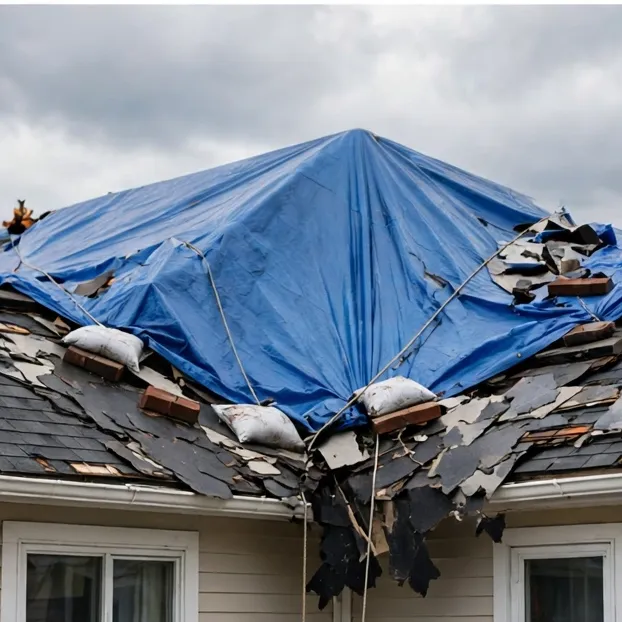
The debris field, the water path, the damaged material itself — that is the evidence. Haul it away before it is photographed and the claim gets argued from memory.
Home / Insurance Claim
Insurance Claim Help · San Rafael, CAA roof claim is won or lost on evidence. Our roof insurance claim San Rafael service documents storm and accident damage the way adjusters need to see it, meets your insurer on the roof, and checks their scope line by line — so the settlement covers the real repair.
We are roofers, not public adjusters or lawyers: we do not negotiate your policy or promise an outcome. What we control is the roof evidence and the repair numbers — and on most claims, that is where the money is lost.
Start with the inspection. You get photos, straight findings, and a written quote — no obligation.
Request a Free Inspection →Open 7 days a week · San Rafael, CA
 Documentation before cleanup
Adjusters often inspect from the ground, or on a ladder, in twenty minutes. Lifted shingles that resealed, cracked tile, the attic-side stain that proves the water path — from the driveway, all of it is invisible. The first scope comes back covering a patch, and the homeowner signs it thinking that is the whole story.
On every roof insurance claim San Rafael file we build, our job is to put the full picture in front of the carrier before that scope is written: dated photographs, a written damage map, and a repair scope that prices the actual work — then to stand on the roof when the adjuster comes, and point.
Every roof insurance claim San Rafael homeowners bring us runs through the same five pieces — because carriers process evidence in a predictable way, and missing steps are what shrink settlements.
Date-stamped close-ups of every damaged area, wide shots of each slope, and attic-side evidence of water entry — taken before cleanup, tarping, or repair disturbs anything.
The damage drawn slope by slope, with the repair scope itemized the way carriers read it: quantities, materials, and the code-required items that first scopes love to omit.
When your carrier schedules their inspection, we are there — on the roof with the adjuster, walking the damage map, making sure nothing on it gets skipped or waved off from the ladder.
When their scope lands short — missing slopes, missing flashing, missing code items — we file a supplement with the photographic evidence and the corrected quantities, and keep the paper trail clean.
Once the claim settles, the same crew that documented the damage makes the permanent repair — so nothing documented gets “value-engineered” out of the job on the way through.
Call us before you clean up. Photos and the damage map come before tarps, buckets get emptied, or debris gets hauled — evidence first, always.
We stop the water with a tarp or temporary seal, invoiced separately — mitigation is usually claimable, and it protects the claim as much as the house.
You file with your carrier (it is your policy and your claim). We give you the documentation file to submit with it.
Your carrier’s adjuster visits; we meet them on the roof with the damage map and walk every item.
Their scope is checked against the real repair. Short? We supplement with evidence. Settled? We do the documented repair.
General information only — your policy is the authority, and every carrier reads it their own way. But the pattern across homeowners policies is consistent enough to plan around:
| Situation | Usually covered? | Why |
|---|---|---|
| Wind tore off shingles in a storm | Generally yes | Sudden, accidental damage from a weather event is the core of the policy. |
| A limb fell and punctured the roof | Generally yes | Impact damage is sudden and documented easily — photograph before removing it, if safe. |
| Storm-driven rain through a storm-made opening | Generally yes | The opening was created by the covered event; the water followed it. |
| A slow leak from an old, worn roof | Generally no | Wear and age are maintenance, and policies exclude them. |
| Damage discovered long after it happened | Often disputed | Late reporting lets the carrier argue neglect. Document and file promptly. |
This table is general education, not coverage advice for your specific policy — your declarations page and your carrier decide your claim. What we provide is the roof-side evidence and repair pricing your claim is evaluated on.
Four mistakes shrink almost every roof insurance claim San Rafael homeowners file. None of them are dishonesty — they are what reasonable people do in a stressful week. Each one costs money.
Ask a Pro →The debris field, the water path, the damaged material itself — that is the evidence. Haul it away before it is photographed and the claim gets argued from memory.
The first scope is a starting position, written fast, often from the ground. Signing off without a roofer’s line-by-line check is how missing slopes and code items stay missing.
An empty roof gets a short inspection. A roofer standing there with a damage map gets a complete one. It is the cheapest hour in the whole claim.
Every storm after the first gives the carrier an argument that the damage is old, mixed, or neglected. File while the timeline is provable.
Bay-wind shingle damage in 94901, oak limbs in the hills, drainage failures on the low-slope roofs of 94903 — storm claims here follow the neighborhoods.
Eichler country — low-slope foam and tar-and-gravel roofs, downspout seams, and recoats on the 94903 side of the hill.
ZIP 94903 · Claim documentationVictorians and Craftsman homes from the 1880s–1910s: layered roofs, tired valleys, and flashing that has earned a rebuild.
ZIP 94901 · Claim documentationTile roofs over aging underlayment, bay-side wind exposure, and larger homes where drainage has to be sized, not guessed.
ZIP 94901 · Claim documentationWhat we can do, what we cannot, and what your carrier will not tell you to do.
Call (628) 202-3250 →The inspection and documentation visit is free — the same free inspection we offer every homeowner. If we then do the repair, the claim work (documentation file, adjuster meeting, scope review, supplements) is part of how we run the job, not a separate percentage or fee. A roof insurance claim San Rafael homeowner hires us to repair does not pay extra for the paperwork.
No — and distrust anyone who does. Approval is your carrier’s decision under your policy. What we guarantee is the evidence: complete documentation, a correct repair scope, and a roofer on the roof when the adjuster is. That is the part of the claim that is actually controllable.
Usually not. Denials and short scopes can be revisited with new evidence — that is what supplements and re-inspections are for. Bring us the carrier’s scope and decision letter; we will compare it against the roof, line by line, and tell you honestly whether the gap is real and documentable.
Policies vary — many require prompt notice and set deadlines commonly around a year from the damage, but your policy is the only authority. Do not gamble on the long end: file while the damage, the dates, and the weather records are easy to line up. If a storm just hit, this week is the right answer.
It depends on the size of the damage against your deductible — and that math should happen before you file. Our free inspection prices the repair first. If the real repair is near or under your deductible, filing gains you nothing. If it is well above it, the documentation we built prices the claim properly.
 ✓
Leak tracing, flashing, tile underlayment, and Eichler foam seam repairs — quoted in writing.
Roof Repair in San Rafael → ✓
Tear-off to the deck, permitted and inspected, in shingle, tile, metal, or low-slope systems.
Roof Replacement in San Rafael → ✓
Free on-roof and attic-side inspections with photos and straight written findings.
Roof Inspection in San Rafael → ✓
Seamless gutters and downspouts sized for atmospheric-river rain.
Gutter Installation in San Rafael →The free inspection builds the evidence file whether you file or not. Call now — and if water is still coming in, say so: dry-in comes first.
Call (628) 202-3250 →Tell us what happened and when. If you have photos already, keep them — and do not climb up to take more.